| ■ 영문 제목 : Iron & Steel Market by Type (Iron and Steel), Iron Production Technology, Steel Production Technology, End-use Industry (Construction & Building, Automotive & Transportation, Consumer Goods, Heavy Industries), and Region - Global Forecast to 2031 | |
 | ■ 상품 코드 : HNI2893MP8883 ■ 조사/발행회사 : MarketsandMarkets ■ 발행일 : 2026년 4월 ■ 페이지수 : 250 ■ 작성언어 : 영어 ■ 보고서 형태 : PDF ■ 납품 방식 : E메일 (주문 후 1영업일) ■ 조사대상 지역 : 글로벌 ■ 산업 분야 : 금속 |
| Single User (1명 열람용) | USD4,950 ⇒환산₩6,682,500 | 견적의뢰/주문/질문 |
| Corporate License (동일기업내 공유가능) | USD8,150 ⇒환산₩11,002,500 | 견적의뢰/주문/질문 |
|
※가격옵션 설명 - 납기는 즉일~2일소요됩니다. 3일이상 소요되는 경우는 별도표기 또는 연락드립니다. - 지불방법은 계좌이체/무통장입금 또는 카드결제입니다. |
| 철강 시장은 2026년 1조 918억 달러에서 2031년 1조 1,594억 달러로 성장할 것으로 전망되며, 이 기간 동안 연평균 성장률(CAGR)은 1.2%를 기록할 것으로 예상됩니다. 철강 수요 증가는 급속한 도시화, 대규모 인프라 개발, 전기차 생산 가속화, 구조용 강재가 필요한 재생에너지 설비 확대, 그리고 스마트 시티, 철도망, 산업 제조 역량 확장을 위한 정부의 지속적인 투자에 기인합니다. 주요 내용 2025년 기준 아시아 태평양 지역이 시장의 64.5%를 차지했습니다. 제품 유형별로는 철강 부문이 예측 기간 동안 가장 큰 비중을 차지할 것으로 예상되며, 2025년 시장 점유율은 63.4%를 기록했다. 철 생산 기술별로는 DRI 공정 부문이 예측 기간 동안 8.2%라는 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망된다. 제강 기술별로는 2025년 기본 산소 용광로 부문이 59.8%를 차지했다. 최종 용도 산업별로는 2025년 건축 및 건설 부문이 30.6%의 점유율을 기록하며 시장을 주도했다. 아르셀로미탈(ArcelorMittal), 중국 바오우 철강 그룹(China Baowu Steel Group), 타타 스틸(Tata Steel), 누코르 코퍼레이션(Nucor Corporation), JSW, 니폰 스틸 코퍼레이션(Nippon Steel Corporation)은 강력한 시장 점유율과 제품 포트폴리오를 바탕으로 전 세계 철강 시장의 주요 기업으로 꼽혔다. 샤강 그룹(Shagang Group), NLMK, 소하르 스틸(Sohar Steel), C.D. 왈츠홀츠(C.D. Wälzholz GmbH & Co. KG), 세베르스탈(Severstal)은 전문적인 틈새 시장에서 강력한 입지를 확보함으로써 신생 기업 및 중소기업 중에서 두각을 나타냈으며, 이는 이들 기업이 신흥 시장 리더로서의 잠재력을 입증하는 것이다. 최종 사용자들이 광범위한 제작, 가공 및 현장 처리가 필요한 기존의 일반 강종에서 벗어나면서, 첨단 철강 솔루션으로의 전환이 점점 더 뚜렷해지고 있습니다. 대신, 이들은 더 빠른 시공, 효율성 향상 및 자재 낭비 감소를 가능하게 하는 고강도 강재, 사전 설계된 구조용 부품, 정밀 가공된 판재 및 장형 제품과 같은 부가가치 제품을 선택하고 있습니다. 동시에 야금 공정, 합금 공학, 표면 처리 기술의 발전은 철강 제품의 성능을 향상시키고 있습니다. 이러한 발전은 더 높은 강도, 우수한 내식성, 향상된 내구성, 더 긴 수명을 제공할 뿐만 아니라 유지보수를 간소화하고 운영 효율성을 높여줍니다. 그 결과, 현대적인 철강 솔루션은 인프라, 자동차, 에너지, 산업 분야 전반에 걸쳐 진화하는 요구 사항에 점점 더 부합하고 있습니다. 고객의 고객에게 영향을 미치는 트렌드 및 혁신 철강 산업은 구조적 변화의 한가운데에 있습니다. 보다 구체적으로 말하면, 기존의 일반용 강재는 점점 더 많은 첨단 맞춤형 강재 시스템으로 대체될 것입니다. 이러한 강재 시스템은 최종 용도에 더 적합하며, 기존의 일반용 강재보다 뛰어난 성능, 단축된 제작 시간, 향상된 설계 유연성을 제공합니다. 여기에는 고강도 구조용 강종, 사전 설계된 부품, 정밀 가공된 판재 및 장형 제품이 포함됩니다. 이러한 새로운 철강 시스템은 신속한 프로젝트 납품 방식, 단계별 시공, 그리고 변화하는 인프라 및 산업 분야의 요구 사항과의 향상된 통합을 통해 건설 속도를 가속화할 것입니다. 또한, 고성능 철강은 향상된 하중 지지 능력, 강화된 내식성, 향상된 치수 일관성, 그리고 현대 공학 및 모듈식 시공 방식과의 향상된 호환성을 포함한 우수한 기계적 특성을 제공합니다. 따라서 철강 산업의 구조적 변화는 수명 주기 전반에 걸친 폐기물과 비효율을 줄이고, 건설 생산성을 높이며, 인프라, 자동차, 에너지 및 기타 산업 응용 분야에 걸쳐 표준화되면서도 유연한 설계를 개발할 수 있는 더 나은 기회를 제공할 것입니다. 급속한 도시화와 변화하는 프로젝트 요구 사항에 따라, 이해관계자들이 다양한 최종 용도 분야에서 내구성이 뛰어나고 효율적이며 고성능인 제품을 요구함에 따라 첨단 철강 제품에 대한 수요는 계속 증가할 것입니다. 시장 생태계 철강 시장 생태계에는 원자재 공급업체(BHP 그룹, 리오 틴토, 발레 S.A., 글렌코어 plc)와 제조업체(아르셀로미탈, 닛폰제철, 타타 스틸, JSW 스틸, 누코어)가 포함되며, 이들은 원자재를 가공하여 산업 전반에 걸쳐 사용되는 평판, 장형, 특수 등급을 포함한 다양한 형태의 금속으로 생산합니다. 유통업체(Ryerson Holding Company, Marubeni-Itochu Steel, Stemcor Group)는 재고로의 입고 및 출고를 조정하고 지역 및 글로벌 규모로 고객에게 제품을 공급하는 한편, 최종 사용자(Toyota Motor Company, Caterpillar, Siemens AG, Larsen and Toubro, Bechtel Corporation)는 구조적 강도, 내구성 및 성능을 위해 금속을 사용합니다. 이 생태계 내 기업들 간의 상호 의존적 관계는 안정적인 자재 공급을 보장하고, 신제품 개발을 위한 혁신을 주도하며, 국내외 인프라 및 산업의 변화에 부응할 것입니다. 상단에 표시된 로고 및 상표는 각 소유자의 재산입니다. 본 문서에서의 사용은 정보 제공 및 예시 목적으로만 제한됩니다. 시장 세분화 철강 시장, 유형별 철강 시장, 제철 기술별 철강 시장, 제강 기술별 철강 시장, 최종 사용 산업별 지역 예측 기간 동안 아시아 태평양이 세계 철강 시장의 최대 지역으로 부상할 전망 아시아 태평양은 강력한 산업화, 급속한 도시화, 대규모 인프라 개발에 힘입어 예측 기간 동안 세계 철강 시장의 최대 지역으로 자리매김할 것으로 예상됩니다. 세계 최대의 철강 소비국인 중국, 인도, 일본, 한국은 방대한 생산 능력을 보유하고 있으며 제조 및 건설 분야에 지속적으로 투자하고 있습니다. 중국은 거대한 통합 제철소와 부동산, 운송, 중공업 등 산업 분야의 강력한 철강 내수 수요 덕분에 단연 세계 최대의 철강 생산국입니다. 인도 역시 인프라 프로젝트, 스마트 시티, 철도, 주택 건설에 대한 정부의 지원으로 철강 산업이 강력한 성장세를 보이고 있습니다. 또한, 해당 지역의 자동차 생산 증가와 재생 에너지 프로젝트 확대는 철강 소비의 추가적인 증가에 기여하고 있습니다. 원자재 확보 용이성, 저비용 노동력, 유리한 산업 정책 등 이 지역의 경쟁 우위는 철강 생산 분야에서 경쟁력을 유지하는 데 도움이 됩니다. 따라서 아시아 태평양 지역은 전 세계 철강 생산 및 소비 양면에서 모든 지역을 계속해서 선도하고 있습니다. 철강 시장: 기업 평가 매트릭스 첨단 야금 기술과 광범위한 제품 포트폴리오를 갖춘 니폰제철(Star)은 철강 산업의 확고한 글로벌 리더입니다. 이 회사는 고효율 고로(blast furnace)를 활용하는 잘 통합된 생산 시스템을 갖추고 있으며, 에너지 효율을 극대화하고 제품 개발을 개선하기 위해 지속적으로 공정을 혁신하고 있습니다. 자동차, 건설, 에너지, 인프라, 조선과 같은 고부가가치 분야에 집중함으로써 철강 업계의 다른 제조사들보다 우위를 점하고 있으며, 글로벌 경쟁력을 강화하고 있습니다. 또한 닛폰제철은 진화하는 산업 및 지속가능성 기준을 충족하기 위해 막대한 연구개발 역량을 바탕으로 경량화, 내구성, 고성능을 갖춘 철강 제품을 공급하고 있습니다. 또한, 확고한 글로벌 공급망을 운영하고 주요 산업 고객사와의 장기적인 관계를 유지함으로써, 닛폰제철은 글로벌 철강 시장에서 강력한 리더십을 확보하고 있습니다. 포스코(신흥 리더)는 저탄소 강재 생산, 수소 기반 기술 활용, 전기로 확대, 제강 공정 디지털화, 지속 가능한 순환 경제 실천 등의 노력을 통해 지속적으로 성장하고 있습니다. |
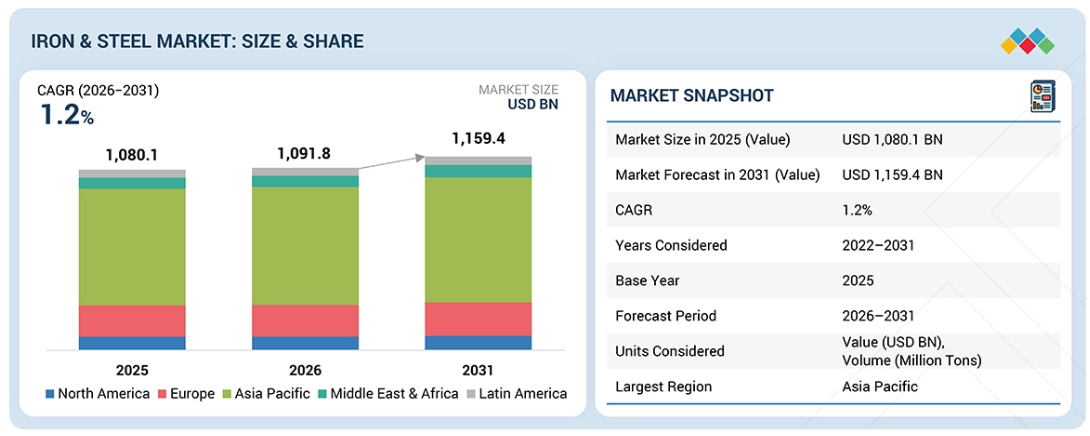
The iron & steel market is projected to grow from USD 1,091.8 billion in 2026 to USD 1,159.4 billion by 2031, representing a CAGR of 1.2% during this period. The demand for iron & steel is attributed to the rapid urbanization, large-scale infrastructure development, accelerating electric vehicle production, expanding renewable energy installations requiring structural steel, and sustained government-led investments in smart cities, rail networks, and industrial manufacturing capacity expansion.
KEY TAKEAWAYS
• Asia Pacific accounted for a 64.5% of the market in 2025.
• By type, the steel segment is expected to be the largest in the forecast period; it held a 63.4% market share in 2025.
• By iron production technology, the DRI process segment is projected to register the highest CAGR of 8.2% during the forecast period.
• By steel production technology, the basic oxygen furnace segment accounted for 59.8% in 2025.
• By end-use industry, the building & construction segment dominated the market in 2025, accounting for a share of 30.6%.
• ArcelorMittal, China Baowu Steel Group, Tata Steel, Nucor Corporation, JSW, and Nippon Steel Corporation were identified as star players in the iron & steel market (global), given their strong market share and product footprint.
• Shagang Group, NLMK, Sohar Steel, C.D. Wälzholz GmbH & Co. KG, and Severstal have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.
The shift toward advanced iron and steel solutions is increasingly evident as end users move away from conventional commodity steel grades that require extensive fabrication, machining, and on-site processing. Instead, they are opting for value-added products such as high-strength steels, pre-engineered structural components, and precision-finished flat and long products that enable faster construction, improved efficiency, and reduced material waste. At the same time, advances in metallurgical processes, alloy engineering, and surface treatment technologies are enhancing the performance of iron and steel products. These developments deliver higher strength, better corrosion resistance, improved durability, and longer service life, while also simplifying maintenance and improving operational efficiency. As a result, modern steel solutions are increasingly aligned with evolving requirements across infrastructure, automotive, energy, and industrial applications.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS’ CUSTOMERS
The iron and steel industry is in the midst of a structural change. More specifically, conventional commodity-grade steel will be replaced by an increasing number of advanced, application-specific steel systems. These steel systems are better suited to the end-use application and provide greater performance, reduced fabrication time, and improved design flexibility than conventional commodity-grade steel. This includes high-strength structural grades, pre-engineered components, and precision-processed flat and long products. These new steel systems will allow construction to move at a faster pace through quicker project delivery methods, phased construction, and improved integration with the changing needs of infrastructure and industrial applications. In addition, high-performance steel offers superior mechanical properties, including increased load-carrying capacity, enhanced corrosion resistance, enhanced dimensional consistency, and improved compatibility with modern engineering and modular construction methods. Therefore, the structural changes in the iron and steel industry will lead to lower lifecycle waste and inefficiencies, higher construction productivity, and better opportunities to develop standardized yet flexible designs across infrastructure, automotive, energy, and other industrial applications. With the rapid rate of urbanization and changing project requirements, the demand for advanced iron and steel products will only increase as stakeholders require long-lasting, efficient, and high-performance products in a variety of end-use applications.
MARKET ECOSYSTEM
The iron and steel market ecosystem includes raw material suppliers (BHP Group, Rio Tinto, Vale S.A., and Glencore plc) and manufacturers (ArcelorMittal, Nippon Steel Corporation, Tata Steel, JSW Steel, and Nucor) that process these inputs into various forms of metal, including flat, long, and specialty grades used across industries. Distributors (Ryerson Holding Company, Marubeni-Itochu Steel, and Stemcor Group) coordinate the movement of materials into and out of inventories and deliver products to customers on a regional and global scale, while end users (Toyota Motor Company, Caterpillar, Siemens AG, Larsen and Toubro, and Bechtel Corporation) use metals for structural strength, durability, and performance. The interdependent relationships among companies within the ecosystem will provide a consistent supply of materials, drive innovation to create new products, and align with changes in domestic and international infrastructure and industries.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Iron & Steel Market, By Type
Iron & Steel Market, By Iron Production Technology
Iron & Steel Market, By Steel Production Technology
Iron & Steel Market, By End-use Industry
REGION
Asia Pacific to be largest region in global iron & steel market during forecast period
Asia Pacific is expected to remain the largest region in the global iron and steel market during the forecast period, driven by strong industrialization, rapid urbanization, and large-scale infrastructure development. As the largest consumers of steel in the world, China, India, Japan, and South Korea have extensive production capacity and ongoing investments in manufacturing and construction. China is by far the largest producer of steel in the world because of its massive integrated steel mills and strong domestic demand for steel in industries such as real estate, transportation, and heavy manufacturing. India is also seeing strong growth in its steel industry due to government support for infrastructure projects, smart cities, railways, and housing. Furthermore, growth in automobile production and renewable energy projects in the region contributes to further increases in steel consumption. The region’s competitive advantages, including the availability of raw materials, low-cost labor, and favorable industrial policies, help it remain competitive in steel production. Therefore, Asia Pacific continues to lead all regions in both, production and consumption of steel globally.
IRON & STEEL MARKET: COMPANY EVALUATION MATRIX
With advanced metallurgical technology and an extensive product portfolio, Nippon Steel Corporation (Star) is an established global leader in the iron and steel industry. The company has a well-integrated production system that uses highly efficient blast furnaces and continually innovates its processes to maximize energy efficiency and improve product development. Its focus on high-value-added applications such as automotive, construction, energy, infrastructure, and shipbuilding gives it an advantage over other manufacturers in the steel industry and enhances its ability to compete globally. Nippon Steel also provides lightweight, durable, and high-performance steel products developed through its significant research & development capabilities to meet evolving industrial and sustainability standards. In addition, by operating a well-established global supply chain and maintaining long-term relationships with key industrial customers, Nippon Steel holds a strong leadership position in the global steel market. POSCO (Emerging Leader) continues to grow through initiatives such as producing low-carbon steel, utilizing hydrogen-based technologies, expanding electric arc furnaces, digitizing the steel-making process, and practicing a sustainable circular economy.
1. Introduction 2. Executive Summary 3. Premium Insights 4. Market Overview 5. Industry Trends 6. Technological Advancements, AI-Driven Impact, Patents, Innovations, and Future Applications 7. Regulatory Landscape and Sustainability Initiatives 8. Customer Landscape and Buyer Behavior 9. Iron and Steel Market, by Type 10. Iron and Steel Market, by Iron Production Technology 11. Iron and Steel Market, by Steel Production Technology 12. Iron and Steel Market, by End-Use Industry 13. Iron and Steel Market, by Region 14. Competitive Landscape 15. Company Profiles 15.2 Other Players 16. Research Methodology 17. Appendix |
| ※본 조사보고서 [세계의 철강 시장 (~2031년)] (코드 : HNI2893MP8883) 판매에 관한 면책사항을 반드시 확인하세요. |
| ※본 조사보고서 [세계의 철강 시장 (~2031년)] 에 대해서 E메일 문의는 여기를 클릭하세요. |
※당 사이트에 없는 자료도 취급 가능한 경우가 많으니 문의 주세요!